 logo

Starting a business is one of the most exciting things an entrepreneur can do. You’re turning your vision into reality, solving problems, and maybe even changing the world. But behind the big dreams, there’s another part of the business that needs attention—your finances. Unfortunately, many startups run into trouble early on because of small financial mistakes. These mistakes may not seem serious at first, but they can create significant problems later. The good news? Most of them are avoidable. Even better, the right tools, such as month-end close software, can make the entire process much easier. In this article, we’ll review five of the most common financial mistakes startups make and how software can help prevent them so your business succeeds.
Mistake 1: Not tracking expenses daily
One of the first things startup founders often forget to do is track their spending daily. You might think, “I’ll catch up at the end of the week,” or “This expense isn’t a big deal.” However, if you delay tracking, the costs quickly add up.
Why is it risky?
Failing to record your expenses regularly leads to two problems: You might overspend without noticing. Second, you may forget to record something important, like a subscription or a vendor payment. When you finally review your budget, things won’t add up. You can’t manage your money if you don’t know where your money is going.
How software helps
Month-end close software can automate expense tracking. You can connect your business accounts, and it will collect data in real time. It also helps categorize each expense so you know what you’re spending on salaries, tools, marketing, or travel. Over time, you will develop a clear picture of your spending habits, which will help you make better decisions.
Mistake 2: Not preparing financial reports monthly
Many startups only think about reports when tax season rolls around. Some may create basic monthly summaries, but not in a consistent or organized way.
Why it’s a problem
Financial reports are like a health check for your business. Without them, you don’t know if your startup is growing, stable, or losing money. Investors also expect reports. It doesn’t create a good impression if you’re ever asked to present your numbers and you don’t have them ready. More importantly, late reporting means delayed action. You may spot a cash drop too late to fix it.
What the right tool does
With month-end close software, you can generate these reports in just a few clicks. The tool pulls your data from different sources and presents it in easy-to-read formats. Most tools include templates for profit and loss statements, balance sheets, and cash flow reports. No need to be a financial expert—you’ll always have a clear and updated view of your company’s status.
Mistake 3: Mixing personal and business money
When you’re starting, it may seem easier to use your personal bank account for business costs. After all, you may not have a lot of expenses yet. But this is a habit that causes big issues later.
Why is it dangerous?
When personal and business funds mix, tracking how much your business is spending or earning becomes hard. It also complicates tax filing. You might miss deductions or, worse, raise red flags during an audit. It can also hurt your credibility with investors, banks, or potential partners.
 How can software help?

With the help of the month-end close software, you can connect only your business accounts. This way, your software tracks and reports only your startup-related income and expenses. Many tools also offer tagging features, so you can label every transaction and keep everything tidy and easy to review later.
Mistake 4: Forgetting to monitor cash flow
Startups often focus on profitability, which is essential. But they forget about cash flow—the money that moves in and out of the business daily.
Why is it a problem?
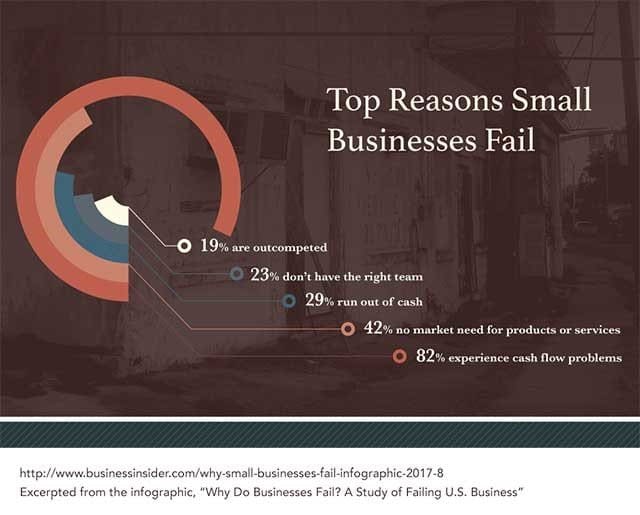
A company can be profitable but still fail if it runs out of cash. For example, you may have sold a product and counted it as income, but the customer hasn’t paid you yet. Meanwhile, you need to pay employees and suppliers. Without enough cash on hand, operations can freeze. You might even miss payroll or lose vendors. In fact, cash flow problems are the number one cause of failure among small businesses.
What can a month-end close software do?
This is where month-end close software proves helpful. It doesn’t just show what you earned and spent. It also tracks when money comes in and needs to go out. The software can show you cash trends over time and highlight slow-paying customers or months with higher expenses than usual. Some even allow you to set reminders for bills and follow-ups for unpaid invoices. Planning becomes easier, and you’re less likely to run into surprises.
Mistake 5: Relying too much on manual work
When you’re a small team, doing your books manually may feel like the cheapest option. But it’s also the most time-consuming and error-prone.
Why is it holding you back?
Manual bookkeeping can lead to mistakes. A small typo or missed entry can affect your reports and lead to bad decisions. It also takes up valuable hours you could spend growing your business or working with clients. As your startup scales, manual work becomes more complicated to manage and easier to mess up.
How does automation make a difference?
With month-end close software, much of the process is automated. Transactions are imported, categorized, and matched to invoices or receipts automatically. Many tools also include error-checking features that notify you if something doesn’t look right. The result? You spend less time doing admin work and more time focusing on your product, customers, or fundraising.
Other benefits of using month-end close software
Besides fixing these five common mistakes, using software from the beginning offers more advantages:
- Saves time: Automating reports, expense tracking, and reconciliation means fewer hours doing repetitive tasks.
- Improves accuracy: Fewer manual entries mean fewer errors. Your numbers are more reliable.
- Boosts investor confidence: If you’re looking for funding, having clean and up-to-date books shows that you’re serious and prepared.
- Supports growth: As your business grows, the software can grow with you. You won’t have to start over with a new system later.
Conclusion
Every startup makes mistakes. That’s part of the journey. But when it comes to finances, a small mistake today can turn into a major problem tomorrow. The five financial mistakes startups make, which we covered—poor tracking, late reports, mixed finances, ignoring cash flow, and manual work—are common. The good news is, they’re also easy to avoid with a bit of discipline and the right tools.
Month-end close software is one of those tools. It doesn’t just save time—it helps you build better habits, gain more visibility, and stay ahead of your finances. Whether you’re a team of one or ten, getting your finances right from the start can be a game-changer.
Need marketing help to support business growth?
We welcome the opportunity to show you how we can make your marketing SIZZLE with our data-driven, results-oriented marketing strategies. Sign up for our FREE newsletter, get our FREE guide to creating an awesome website, or contact us for more information on hiring us.
Hausman and Associates, the publisher of MKT Maven, is a full-service marketing agency operating at the intersection of marketing and digital media. Check out our full range of services.
Discover more from MKT Maven
Subscribe to get the latest posts sent to your email.


